Gold Loan Locker Facilities: Your Complete Guide to Security, Fees, Insurance & Process
15 September, 2026 Gold Loan
10 mins read
Discover everything about gold loan locker facilities. Learn how lenders secure your pledged gold, understand eligibility criteria, hidden fees, insurance coverage, and the step-by-step process to make confident financial decisions.
If you’ve ever considered using your gold as collateral for a loan, you’ve probably already heard about gold loan locker facilities. Yet, you might be missing critical details about how these facilities protect your assets and streamline the loan process. In this guide, we'll explain everything you need to know about gold loan locker facilities to help you make confident financial decisions.
Key Takeaways
- A gold loan locker facility is the lender’s secure vault storage for your pledged jewellery until the loan is repaid.
- Most lenders include locker usage in the loan process; separate applications are rarely needed.
- First-year locker charges are often waived; annual fees may apply afterward (e.g., around ₹300 in some safe-lock variants).
- Pledged gold is sealed, logged, and stored under surveillance; some lenders use OTP-controlled e-lockers for added security.
- Eligibility typically requires Indian citizenship, age 18 - 75, and gold purity above 18 carats.
- Insurance coverage for pledged jewellery is a key benefit offered by select lenders.
- Before applying, confirm security features, fees after year one, and whether insurance is included.
What Is a Gold Loan Locker Facility and How Does It Work?
A gold loan locker facility is the lender's secure vault storage for pledged jewellery during the loan term, which is often incorporated in the loan procedure without requiring a separate application. When you take out a gold loan, the lender stores your gold goods as physical collateral in high-security strong rooms rather than allowing you to retain them at home. In India, institutional gold loan portfolios increased by more than 21% year on year as borrowers sought collateralized lending
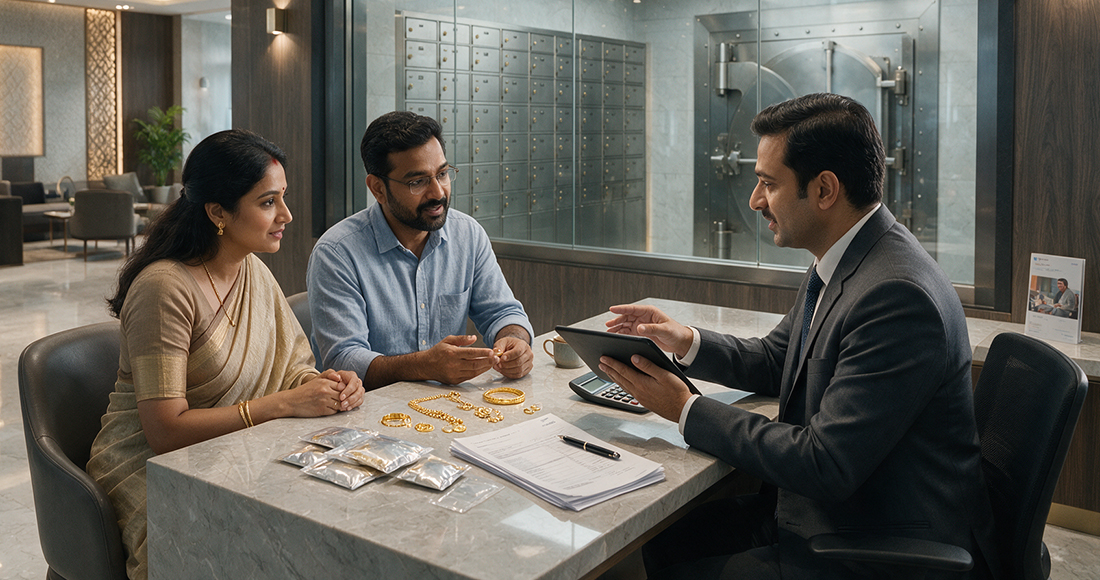
To begin with, the storage process is directly integrated into the overall loan evaluation workflow. For example, when a customer visits a branch, an authorized appraiser tests the gold’s purity, weighs the ornament, and calculates the eligible loan amount. Once approved, the gold is placed inside a heavy-duty, tamper-evident pouch right in front of you. [how gold loans are processed]
Furthermore, the sealed pouch is allocated a unique tracking barcode and stored in an internal branch safe or high-security locker vault. For example, the borrower receives an inventory receipt that specifies each ornament's weight and corresponding packet ID number. This approach provides complete responsibility from the time you hand up your jewellery until you retrieve it.
Why Gold Loan Locker Facilities Matter
Gold loan lockers are important because they protect your high-value family possessions from theft, damage, and loss while providing as collateral for speedy cash. Storing precious metals in domestic safes puts families at risk for burglary and accidental loss. According to studies, home burglaries account for roughly 70% of all reported property crimes in urban areas (National Crime Records Bureau, 2023).
In addition, institutional storage provides environmental protection that individual homes cannot match. Specialized strong rooms, for example, keep gold ornaments safe from dampness, structural damage, and inadvertent displacement. This level of security relieves borrowers of the everyday anxiety that comes with protecting valuable ancestral jewellery at home.
Furthermore, skilled vault storage builds institutional confidence between the borrower and the Non-Banking Financial Company (NBFC) or bank. For example, knowing that pledged gold is secured behind reinforced steel doors and dual-key custody systems reassures borrowers who may be hesitant to pledge family assets. This fundamental trust distinguishes gold loans as one of the most dependable secured credit solutions in the country.
Who Is Eligible for a Gold Loan with Locker Storage?
Eligibility for a gold loan locker facility generally requires Indian citizenship, age between 18 and 75, and gold purity above 18 carats. Because the loan is fully secured by physical collateral, lenders do not place primary emphasis on traditional credit scores like CIBIL. Over 80% of gold loan applicants in Tier 2 and Tier 3 cities obtain approval without extensive formal income documentation
First, age and citizenship parameters are designed to be universally accessible across demographics. For example, salaried professionals, self-employed business owners, agricultural workers, and retirees are all equally eligible to apply. [gold loan eligibility criteria → https://www.kosamattam.com/eligibility-calculator]
Second, the quality of the gold itself serves as the decisive factor for vault acceptance and loan limits. For instance, lenders evaluate ornaments using karat meters to verify that the purity ranges between 18K and 24K.
How Gold Loan Locker Facilities Work (Step-by-Step)
Gold loan locker facilities work through a standardized sequence: application, KYC, appraisal, sealing/packeting, vault storage, acknowledgement, repayment, and release. Understanding each step helps you spot red flags and ask the right questions at the branch.
Step 1: Application and KYC
First, you fill out a loan application form with personal details. Next, you submit KYC documents (Aadhaar, PAN, address proof).
Step 2: Gold Appraisal and Purity Check
Then, the lender weighs your ornaments and checks purity (often via XRF or karat testing). This step determines your loan-to-value ratio and interest slab.
Step 3: Sealing, Packeting, and Vault Storage
After appraisal, the gold is sealed in a tamper-evident packet with a unique ID and moved to a controlled vault. Pledged gold packets are sealed at the counter, moved to a controlled vault, and tracked through custody logs with surveillance and periodic audits
Step 4: Acknowledgement and Receipt
You receive an acknowledgement or receipt that references your packet ID and loan account. Keep this document safe; you’ll need it during repayment and release.
Step 5: Repayment and Release of Gold
Finally, once you repay the principal and interest, the lender retrieves your packet, verifies the seal and ID, and returns the ornaments.
Types of Gold Loan Locker Arrangements
Gold loan locker arrangements vary by lender and can include in-branch vaults, centralized locker units, OTP-controlled e-Lockers, and third-party premium locker tie-ups. Knowing the type your lender uses helps you gauge security and convenience.
In-Branch Vaults
First, many lenders store pledged gold in secure vaults located within the branch premises. These vaults typically have restricted access, CCTV coverage, and dual-control protocols.
Centralized Locker Units
Second, some institutions operate centralized gold locker units where ornaments from multiple branches are stored in a single high-security facility. This model can improve auditability and reduce branch-level risk.
e-Lockers with OTP Access
Third, a growing number of lenders use e-Lockers integrated with centralized servers, so lockers open only after system verification and customer authentication. Some lenders implement OTP-controlled e-Lockers integrated with centralized servers, ensuring lockers open only after system verification and customer authentication.
Third-Party Premium Locker Tie-Ups
Finally, certain safe-lock variants partner with third-party locker providers to offer additional storage options, sometimes with nominal annual fees (e.g., around ₹300/year)
What Are the Benefits of Using Gold Loan Locker Facilities?
Gold loan locker facilities offer multiple benefits that improve the borrowing experience and asset security.
- Enhanced Security: Your gold is kept in a high-security environment, reducing theft and loss risks.
- Convenience: No need to physically transport gold for each transaction.
- Transparency: Regular inspections and documentation maintain clear records of your gold.
- Faster Loan Processing: Since gold is already secured, approvals and disbursals happen faster.
- Peace of Mind: You retain ownership and access to your gold throughout the loan term.
Are Gold Loan Locker Charges Free or Included in the Loan?
Many financial institutions waive gold locker charges in the first year, with annual fees imposed on the customer afterward (e.g., around ₹300 in some safe-lock variants). Understanding fee schedules prevents unexpected deductions when you close your loan. In standard retail gold loans, storage costs account for less than 0.5% of the overall transaction expense
First, locker facilities are typically bundled into the primary loan processing setup rather than billed as an upfront subscription. For example, major lenders offer "Safe Lock" schemes where storage is free during initial months but carries nominal maintenance fees if the loan extends past 12 months.
Second, borrowers must carefully review fee disclosures for potential hidden costs. For instance, while basic custody is included, certain lenders charge small administrative fees for mid-tenure gold inspections or partial withdrawals. Checking these terms in advance helps you compare the total cost of credit across different institutions.
Do Lenders Provide Insurance for Pledged Gold Jewellery?
Most reputed Non-Banking Financial Companies (NBFCs) and banks provide comprehensive insurance coverage for pledged gold jewellery at no additional direct cost to the borrower. This financial safeguard protects your assets against theft, armed robbery, fire, and natural disasters while stored in the vault. Commercial crime insurance policies for institutional vaults cover up to 100% of the market value of stored collateral.
In addition, insurance policies are tied directly to the appraised market value of your ornaments at the time of pledge. For example, if an unforeseen incident affects a branch vault, the insurance underwriter reimburses the lender, who in turn compensates the borrower based on the agreed valuation log.
Consequently, this blanket insurance coverage gives gold loan lockers a major security advantage over unorganized private pawnbrokers. For instance, private moneylenders rarely maintain formal insurance policies, leaving borrowers vulnerable to total loss if theft occurs. Institutional insurance guarantees that your wealth remains fully protected under all circumstances.
Bank Locker Vs Gold Loan Locker: What Is the Difference?
|
Feature / Metric |
Standard Bank Safe Deposit Locker |
Gold Loan Locker Facility |
|
Primary Purpose |
Personal safekeeping of valuables |
Storage of pledged collateral for credit |
|
Upfront Cost / Fees |
Annual rental fee (₹1,500 to ₹10,000+) |
Often free in Year 1; nominal fee post-Year 1 |
|
Liquidity Provided |
None (Costs money to hold) |
Immediate cash disbursal against gold value |
|
Availability / Waitlist |
High demand; long waiting lists in branches |
Instant access upon gold loan application |
|
Insurance Coverage |
Optional / Limited bank liability |
Comprehensive institutional insurance included |
|
Access Rights |
Customer holds key; access anytime during branch hours |
Vault unlocked upon full loan repayment |
How to Choose a Lender with the Best Gold Storage Security?
Choosing a lender with top-tier gold storage security requires evaluating vault infrastructure, insurance transparency, locker fee schedules, and branch audit frequencies. Selecting the right financial partner prevents future disputes and ensures seamless custody management. Non-banking financial companies operate over 30,000 specialized gold loan branches across India - Source: Associated Chambers of Commerce and Industry of India, 2024.
Let's explore how to evaluate different institutions - “NBFC vs bank gold loans"
First, inspect the branch security measures in person when you submit your gold. For example, verify whether the branch features CCTV cameras covering the counter, electronic access control doors, and professional security personnel.
Second, examine the lender's reputation regarding packet sealing and handling practices. For instance, reputable institutions always weigh and seal gold in your direct line of sight using calibrated digital scales that display weight up to two decimal places. Choosing a transparent lender eliminates doubts regarding ornament care and weight accuracy.
What Happens to Your Gold After Full Repayment of the Loan?
After full repayment, your gold is retrieved from the vault, the seal and ID are verified against your records, and the ornaments are returned to you. The release process is designed to be as secure as the storage process.
Release Workflow at a Glance
First, you request closure and pay any outstanding interest or charges. Second, the branch retrieves your packet and verifies the seal number. Third, you sign an acknowledgement upon receipt.
Checklist Before Applying: What Steps Should You Take Next?
Before applying for a gold loan, borrowers should follow a structured evaluation process to verify storage safety, charges, and retrieval protocols. Taking these practical steps prevents surprises and streamlines your loan experience.
1. Compare Storage Costs: Inquire whether locker usage is completely free in the first year and ask about annual charges thereafter.
2. Verify Insurance Terms: Confirm that the lender maintains active insurance policies covering the full market value of pledged assets.
3. Inspect Sealing Protocols: Ensure the branch seals gold packets in front of you using numbered, tamper-evident bags.
4. Check Scale Calibration: Confirm that the branch uses certified digital weighing scales with visible customer displays.
5. Review Renewal Options: Understand what happens to locker storage if you decide to extend or roll over your loan tenure.
6. Bookmark Helpful FAQs: Keep reference guides accessible to address any questions during your loan tenure. ["gold loan FAQs”]
Conclusion
Reputable financial institutions accept pledged gold as high-security collateral, ensuring total protection during the term of your loan. Gold loan locker facilities provide a valuable dual benefit: they convert dormant gold jewellery into active liquidity while also providing institutional vault safety superior to residential storage. Understanding how packets are sealed, tracked, insured, and billed allows you to confidently select a reputable lender and obtain the monies you require without worrying about your family's valuable treasures.
FAQ
1) What is a gold loan locker facility?
A gold loan locker facility is the lender’s secure storage for pledged jewellery—sealed packets kept in a controlled vault with access logs, surveillance, and periodic audits until you close the loan
2) Do I need to apply separately for the locker?
No. In most cases, the locker facility is included in the gold loan process and does not require a separate application.
3) Are there locker charges, and when do they apply?
Many lenders waive locker charges in the first year; annual fees may be imposed afterward (some safe-lock variants charge around ₹300/year).
4) Is my pledged gold safe in the lender’s vault?
Yes, when the lender uses sealed packets, custody logs, surveillance, dual-control access, and periodic audits, pledged gold is stored securely.
5) Do lenders provide insurance for pledged jewellery?
Some lenders offer insurance coverage for pledged jewellery as a benefit; confirm this before you sign.
6) What documents are needed to avail the locker facility?
You typically need a filled gold loan application form, identity proof, address proof, passport-sized photographs (if required), and bank account details for disbursement/repayment.
7) Who is eligible for a gold loan locker facility?
Eligibility generally requires Indian citizenship, age between 18 and 75, and gold purity above 18 carats that can be pledged as security.
8) How are gold packets sealed and tracked?
Packets are sealed at the counter with a unique ID, the seal number is recorded, and movements are tracked via custody logs and surveillance.
9) What happens after I repay the loan in full?
After full repayment, your packet is retrieved, the seal and ID are verified, and the ornaments are returned to you against acknowledgement.
10) Can I visit the vault or see my gold during the loan tenure?
No. Viewing is typically restricted to protect custody integrity; access is lender-controlled until closure.